PANDEY NIVESH • HEALTH COVER
A health policy should be understood before you need it.
The right questions today can prevent confusion during a stressful hospital visit.
Health insurance is a contract. The policy schedule, wording and endorsements—not an advertisement alone—explain what is covered and under what conditions.
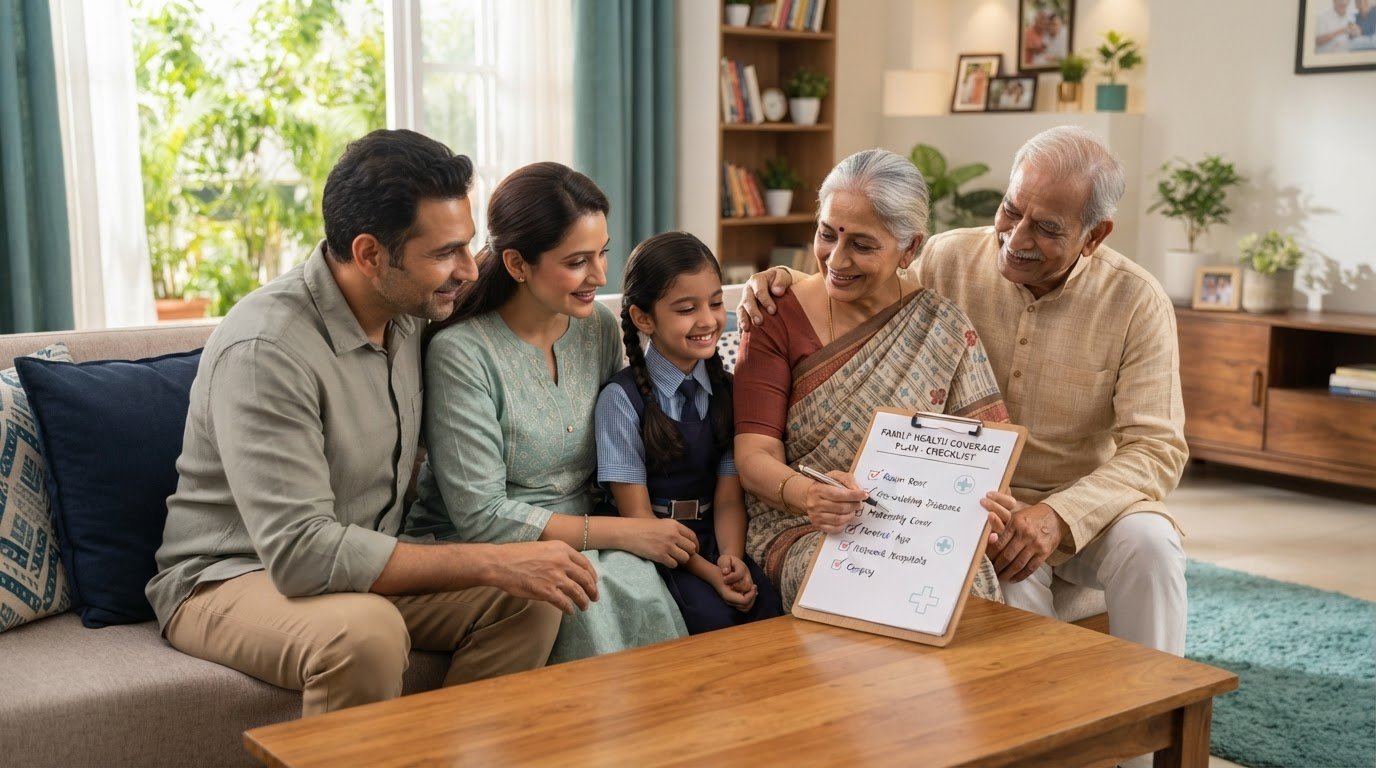
Seven details to compare
- Waiting periods: Initial, specified-disease and pre-existing-disease waiting periods may differ.
- Co-payment: Check whether you must pay a stated share of admissible expenses.
- Room eligibility: Understand room category limits and any proportionate deduction clauses.
- Exclusions: Read permanent and specific exclusions carefully.
- Network hospitals: Check current cashless network access near home and work.
- Restoration benefit: Confirm when it triggers, whether it applies to the same illness and who can use it.
- Renewal terms: Understand lifelong renewability, premium changes and portability rules.
Practical bill example
Imagine a hospital bill contains room charges, doctor fees, diagnostics and medicines. The amount payable by the insurer can differ from the total bill because of policy limits, exclusions, non-payable items, co-payments and admissibility rules. Always ask for a written estimate and check the policy conditions; never assume the full bill will automatically be paid.
Before buying or renewing
- Disclose medical history accurately.
- Compare family floater and individual cover based on family members’ needs.
- Check sub-limits, disease-wise caps, deductibles and restoration conditions.
- Keep policy number, insurer helpline and claim process accessible.
Educational information only. Policy terms vary by insurer and product. Verify the latest policy wording and Customer Information Sheet before purchase or renewal.