LIC’s Jeevan Utsav is a non-linked, non-participating, individual savings whole-life insurance plan. It combines life cover with a choice of Regular Income Benefit or Flexi Income Benefit, subject to the policy terms. This guide explains the current Plan 771 (UIN 512N363V02) in simple language, with an illustrative example taken from LIC’s brochure.


At a glance: what does Jeevan Utsav offer?
- Whole-life insurance cover with limited premium payment.
- Premium-paying term choices from 5 to 16 years.
- Guaranteed Additions during the premium-paying term, at the rate specified in the brochure.
- Choose Regular Income Benefit or Flexi Income Benefit at policy inception.
- Optional riders may be available for additional premium; policy loan facility is subject to policy conditions.
- Minimum Basic Sum Assured: ₹5 lakh.
Practical example: age 30, ₹5 lakh Basic Sum Assured
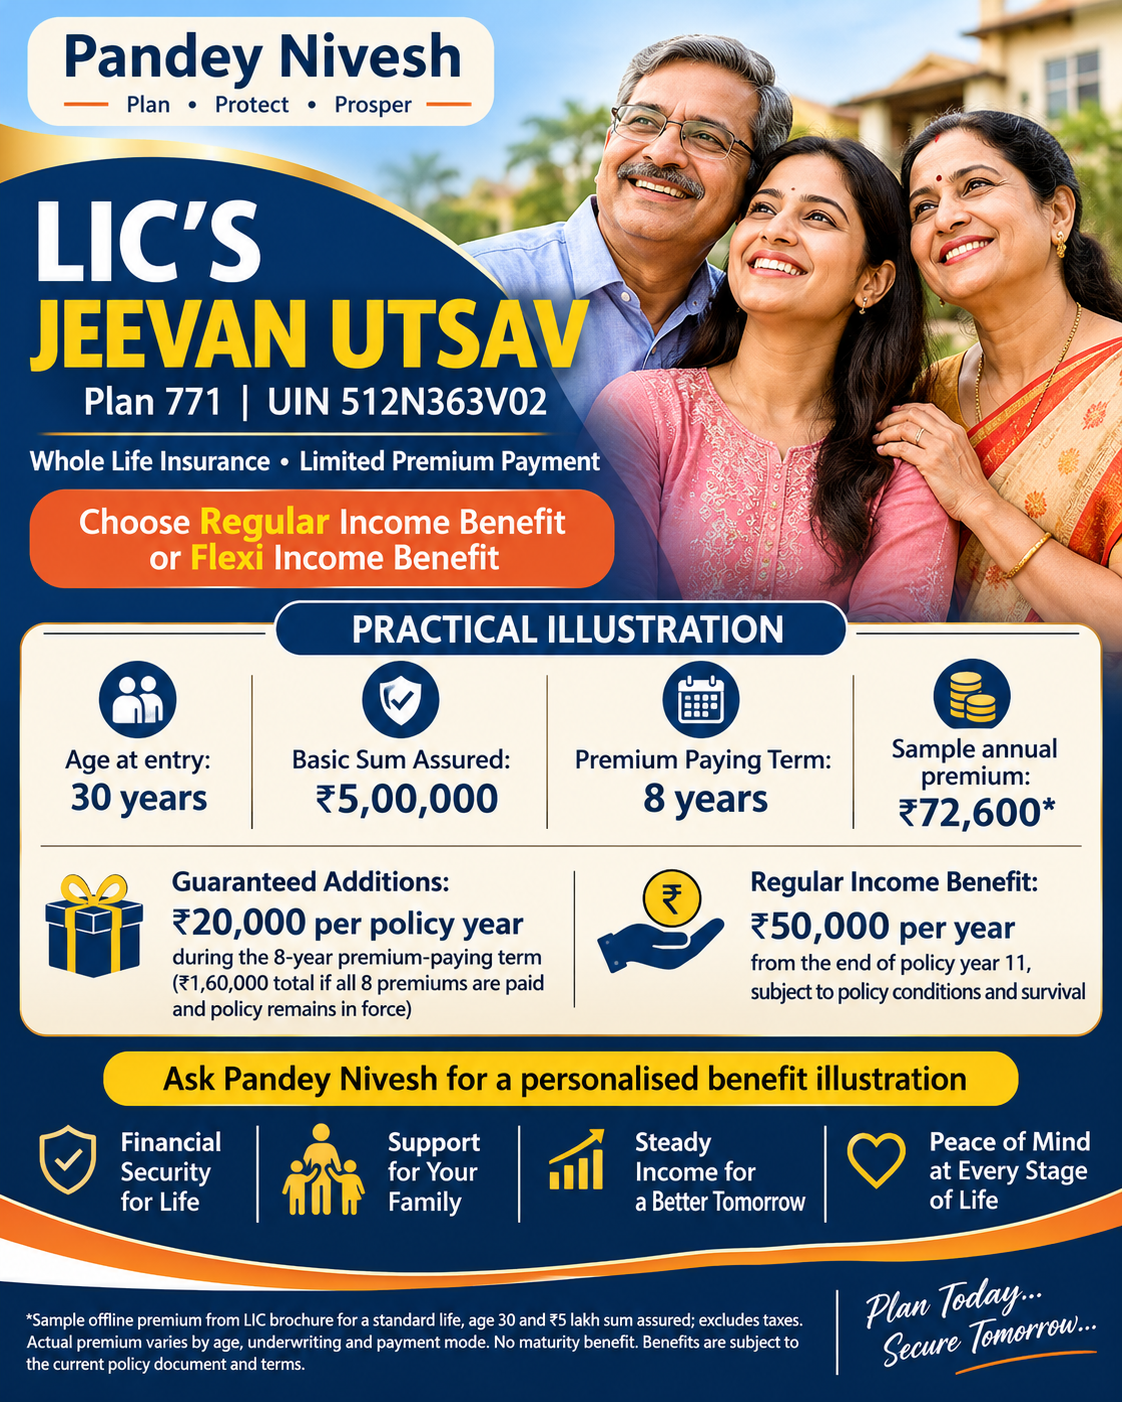
The following is a sample illustration from LIC’s brochure for a standard life, age 30, offline sale, ₹5,00,000 Basic Sum Assured and an 8-year premium-paying term. It is not a personalised quotation.
| Illustration detail | Amount / timing |
|---|---|
| Age at entry | 30 years |
| Basic Sum Assured | ₹5,00,000 |
| Premium-paying term | 8 years |
| Sample annual premium | ₹72,600 (excluding taxes) |
| Approx. total of 8 annual premiums | ₹5,80,800 (excluding taxes) |
| Guaranteed Addition rate | ₹40 per ₹1,000 of Basic Sum Assured per policy year during the premium-paying term |
| Illustrative Guaranteed Additions | ₹20,000 per year × 8 years = ₹1,60,000, if all premiums are paid and the policy remains eligible/in force |
| Regular Income Benefit | ₹50,000 per year (10% of ₹5,00,000), starting at the end of policy year 11, subject to survival and policy conditions |
Important: ₹50,000 is 10% of the Basic Sum Assured, not 10% of the premium paid and not an investment-return rate. For an 8-year premium-paying term, the first Regular Income Benefit is due at the end of policy year 11. The sample premium is from LIC’s published illustration and actual premium can differ by age, underwriting, payment frequency, applicable loadings and taxes.
Regular Income or Flexi Income: what is the difference?
Regular Income Benefit: the eligible annual income benefit is paid each policy year from the applicable start year while the life assured survives and the policy conditions are met.
Flexi Income Benefit: the policyholder may defer and accumulate eligible income benefits instead of taking them immediately. LIC’s brochure specifies interest of 5.5% per annum, compounded yearly, on deferred and accumulated Flexi Income Benefits, with withdrawals and other conditions governed by the policy.
What should you understand before buying?
- No maturity benefit: LIC’s brochure states that no maturity benefit is payable under this plan. Do not buy it expecting a maturity lump sum.
- Long-term commitment: choose a premium-paying term only after checking that the premiums comfortably fit your budget.
- Death benefit: the policy provides a death benefit based on the higher of Basic Sum Assured or 7 times Annualised Premium, plus accrued Guaranteed Additions, subject to the minimum benefit and detailed policy conditions.
- Guaranteed Additions: these accrue only during the premium-paying term while the policy remains eligible/in force; they do not continue indefinitely after premiums stop.
- Riders and loans: optional riders cost extra, and loan availability/amount are subject to LIC’s rules.
- Compare your needs: if your main need is a large amount of life cover at a lower cost, compare a suitable pure term insurance option separately. If you need a maturity lump sum or early liquidity, compare other products too.
Who may consider this plan?
It may be worth evaluating for someone who wants whole-life insurance with a limited premium-paying period and a later income benefit, and who can maintain the premium commitment. It may not suit someone who needs a short-term investment, a maturity payout, or easy access to the money in the early years. Suitability depends on age, income, family responsibilities, existing cover and financial goals.
अक्सर पूछे जाने वाले प्रश्न
Is Jeevan Utsav a market-linked plan?
No. LIC describes Plan 771 as non-linked and non-participating. Benefits are defined by the policy terms; it is not a mutual fund or a market-linked investment.
Does it pay 10% of the premium every year?
No. The Regular Income Benefit is 10% of the Basic Sum Assured, subject to the selected option, the start year for the chosen premium-paying term, survival and policy conditions.
When does the income start?
For a 5-, 6-, 7- or 8-year premium-paying term, the first Regular/Flexi Income Benefit is due at the end of policy year 11. Longer premium-paying terms have later start years as shown in LIC’s brochure.
Ask Pandey Nivesh for a personalised illustration
Share your age, preferred Basic Sum Assured and affordable premium range. We can help you understand the applicable premium illustration, income start year, death benefit, conditions and whether the plan fits your needs. There is no obligation to purchase.